

A carmaker is joining the race to refill America’s weapons arsenal…
Detroit-based General Motors (GM) has started making parts for Patriot missiles. In August, its defense unit delivered the first batch of missile housing components to Lockheed Martin (LMT).
It took just 22 days for GM to fill the order after the companies signed a contract. That speed matters.
Inventories can shrink quickly during a conflict. So the U.S. needs more missiles… and the defense companies that make them need more production capacity.
Money alone won’t refill them. Factories need suppliers that can deliver large orders reliably.
GM knows how to do that. Its plants produce millions of vehicles a year, each assembled from thousands of parts. Now the company is putting some of that manufacturing experience to work for a missile maker.
Today, we’ll explain why GM’s move into missile-parts production could strengthen its business… and why investors may be overlooking the opportunity.
GM Doesn’t Need Much to Surprise Investors
Missile makers need more than new orders…
Lockheed plans to increase its annual production capacity for PAC-3 MSE interceptors from roughly 600 to 2,000 under a seven-year agreement with the government. That takes more equipment, more workers, and a dependable supply of components to its factories.
GM has begun supplying cast and machined parts that form the missile’s housing. The first delivery – which, again, only took 22 days – shows just how quickly an established manufacturer can join that supply chain. The two companies also plan to explore work on other defense systems.
The GM Defense subsidiary already sells military vehicles, including trucks used to transport troops. Missile components give it another way to apply its parent company’s engineering and manufacturing capabilities. And if this first project leads to larger orders, GM could build a more substantial defense-supply business over time.
That’s a compelling possibility for a company with lackluster profitability…
Last year, Lockheed generated a 20% Uniform return on assets (“ROA”). GM generated just 6%.
At Altimetry, we analyze earnings with Uniform Accounting to avoid the distortions of traditional accounting methods.
That 6% figure is a company-wide return, so it doesn’t tell us what GM could earn building missile components. Still, it shows the difference between what a large defense contractor and an automaker can earn.
A growing defense business could give GM another source of earnings alongside the more cyclical car market, which could boost its ROA.
Yet investors expect GM’s overall returns to head the other way…
We can see this through our Embedded Expectations Analysis (“EEA”) framework.
The EEA starts by looking at a company’s current stock price. From there, we can calculate what the market expects from the company’s future cash flows. We then compare that with our own cash-flow projections.
In short, it tells us how well a company has to perform in the future to be worth what the market is paying for it today.
GM’s stock price implies that its Uniform ROA will fall from about 6% last year to less than 4% by 2030.
In other words, investors believe GM’s business will deteriorate, even though it has a new growth avenue.
Take a look…
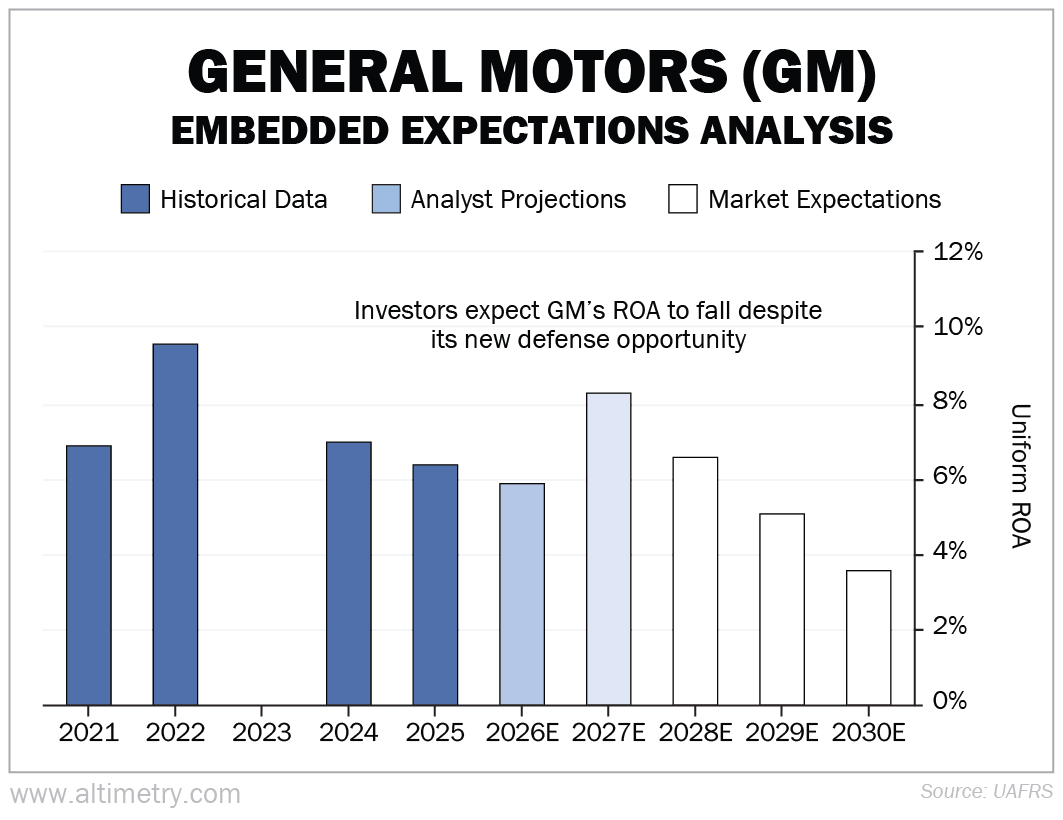 GM has to do very little to beat that 4% prediction. If returns simply hold near today’s level, the stock could outperform. Add in a larger, profitable defense business, and GM has a chance to surprise investors.
The first shipment of missile parts to Lockheed won’t transform a company of GM’s size. It’s an early step. The size and profitability of future defense orders remain to be seen.
Still, the U.S. desperately needs to rebuild its missile inventory. GM has already shown it can make critical missile components quickly, and Lockheed is preparing for a substantial increase in output. More orders could follow if GM proves it can deliver reliably.
Meanwhile, the market believes GM’s returns will decline. That leaves room for a surprise if the company’s car business simply holds steady. And if building missile parts becomes a reliable source of income, the upside could be much larger.
GM doesn’t need to become Lockheed for investors to benefit. Its stock can soar as long as the company beats the market’s low expectations.
Regards,
Joel Litman
For years, we've been led to believe the tech firm operating at 500 Howard Street in Silicon Valley is "one of the good guys." But will the advanced form of AI that just emerged from this location change the way we live, work and invest forever? Marc Chaikin reveals the time-sensitive details of this discovery and offers you a FREE 3-part playbook to protect your future. Click here for the details.
Source: Daily Wealth
