

T. Rowe Price (Nasdaq: TROW) manages $1.8 trillion for clients and offers more than 100 mutual funds and ETFs.
The stock sports a generous 5% yield. Let’s see if that yield is likely to be maintained.
T. Rowe Price generated $1.5 billion in free cash flow in 2025, which was a 17% increase over 2024. However, the three-year growth rate was negative, as the company’s free cash flow totaled $2.1 billion in 2022.
The Safety Net model penalizes a company if its free cash flow growth is negative over one- and three-year periods, so T. Rowe Price’s three-year growth rate causes a downgrade.
The asset manager gets another downgrade because free cash flow is forecast to decline to $1.4 billion this year. If free cash flow comes in higher than last year’s figure, that penalty will be removed, but we won’t see the 2026 results for about a year.
In 2025, the company paid shareholders $1.1 billion for a payout ratio of 77%. That is just above the 75% cutoff, so the stock gets whacked with another downgrade.
This year, with cash flow expected to decline, the payout ratio is projected to increase to 82%, pulling further away from the comfort zone. That’s another downgrade.
The good news is that T. Rowe Price has raised its dividend every year for an impressive 40 years.
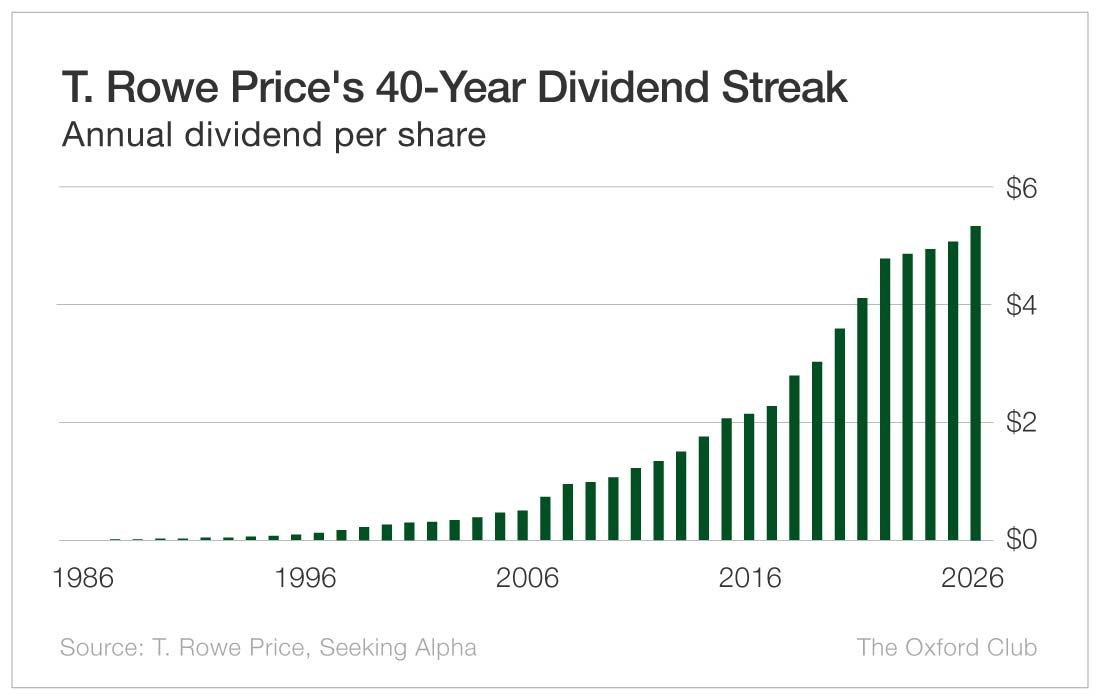 Management clearly takes its dividend-raising history seriously.
In 2023, dividends paid exceeded free cash flow, and the same thing nearly happened again in 2024. Yet the company continued to raise the dividend (though only by $0.02 in order to keep the streak alive).
The financials say the dividend is at risk. Management’s actions when it comes to boosting the dividend say otherwise.
If T. Rowe Price can get back to positive free cash flow growth, that will take some of the pressure off of the dividend rating. If not, management will have some tough decisions in the future.
I don’t expect a cut right away, but at this point, the dividend cannot be considered safe.
Dividend Safety Rating: D
 — Marc Lichtenfeld
There's a good chance that Elon Musk, Sam Altman, and Jensen Huang NEED this stock to fulfill their ambitions. Which is why Marc Chaikin –who recommended Nvidia before its 21,000% run-up – is predicting this could be the biggest winner of the new year. He's sharing the name and ticker, free of charge, with no strings attached. Click here to see why he's calling this his No. 1 stock idea for 2027.
Source: Wealthy Retirement
